TERM INSURANCE PLAN
Without Income Proof

Finding the right financial safety net to keep your loved ones protected is vital, especially if you don’t have formal income records. A term insurance plan without income proof bridges this gap and offers financial protection with minimal documentation and no income proof barriers.
Can you purchase term insurance without income proof?
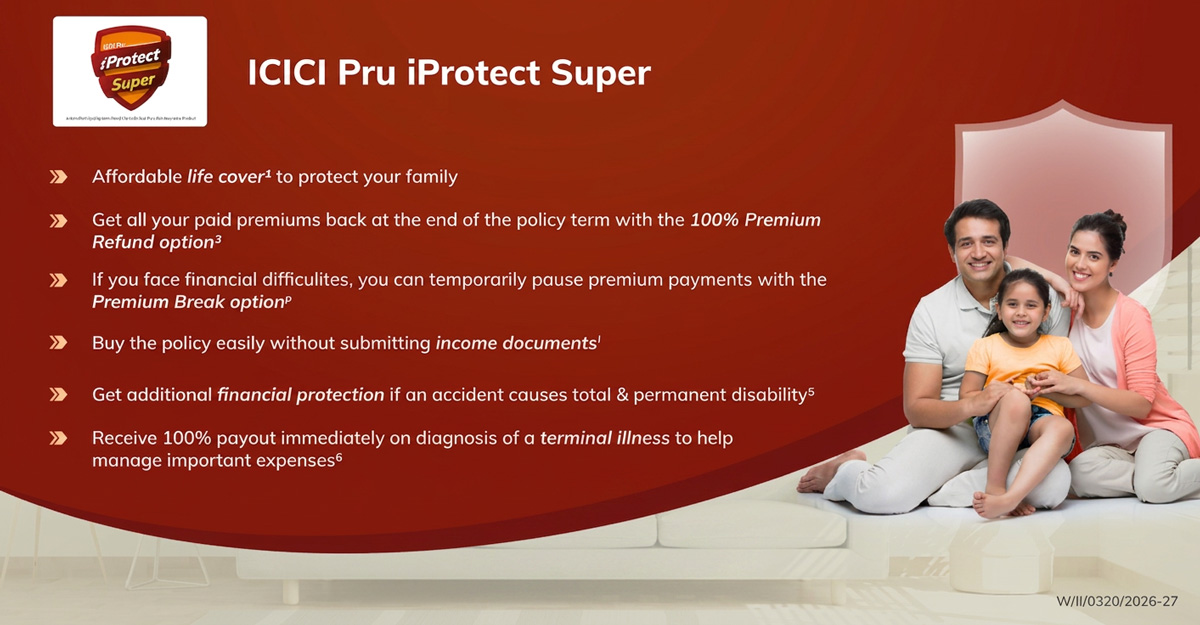
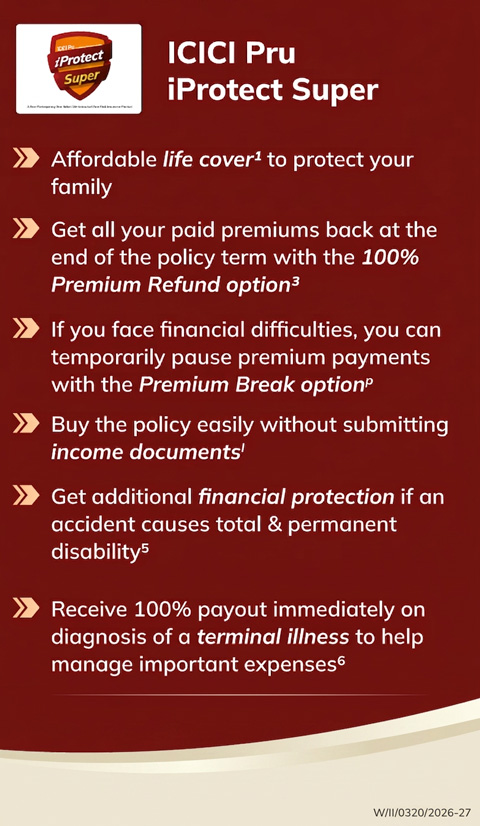
If you are gainfully employed but lack consistent income records, you can still buy term insurance without income proof. This policy provides your family with essential financial security during unforeseen events. It is a reliable option designed specifically for individuals without traditional income documentsl.
Features such as minimal paperwork and no mandatory income proof make the term insurance without income proof more accessible. Additionally, these features offer greater flexibility and streamlined processes, making it easier to buy life insurance without proof of income.
Why consider term insurance without income proof?
Securing financial protection can be difficult for many individuals without conventional income documentation. Freelancers, small business owners, and those without regular income records may often face such challenges.
A term insurance plan without income proof ensures that even their families remain safeguarded. Protection is available even without salary slips or tax returns. These plans highlight the importance of coverage despite documentation limitations. They offer peace of mind and a reliable safety net.
What are the benefits of buying a term plan that requires minimal documentation?
Buying a term insurance plan without proof of income is a hassle-free way to protect your family’s future. These plans are designed to cut down complexities, especially for those without conventional income records.
Such term insurance plans provide comprehensive coverage with lower documentation requirements and simplified processes. This also makes insurance more accessible to a wider audience.

Minimal paperwork
Traditional insurance plans often require extensive paperwork. With term insurance without ITR, you only need basic identification like Aadhaar and PAN cards.
This streamlined process is designed for individuals without regular financial records like a salary. Hence, it makes it easier for them to secure term life insurance without income proof effortlessly.

Quick approval process
Not having a consistent income record shouldn’t be a constraint to get policy approvals. Term insurance without income proof speeds up this process by simplifying document verification.
Minimal paperwork means that you can receive approval quickly, providing peace of mind. It also enables you to secure your family’s financial future without unnecessary waiting periods.

Flexible payments
Flexibility in premium payments is a key benefit of term insurance plans without income proof. These plans allow you to choose payment schedules that match your income pattern.
Whether you prefer monthly, semi-annual, or yearly payments, these options are designed to suit individuals with irregular income.

Accessibility
Buying term insurance without income proof online makes the process seamless. You can easily compare plans, upload minimal documents required, and secure insurance coverage from the comfort of your home. Such high level of convenience saves time and ensures a smooth experience, especially for busy self-employed individuals.
How does term insurance without income proof work?
Insurers may use multiple ways to evaluate risks if you do not have an income document. They can consider factors such as age, health condition and basic financial indicators. Instead of salary slips or tax returns, they can consider alternatives such as credit scores, credit history, medical reports and identification documents.
The premiums required for such plans can vary depending on the insurer’s evaluation, while the life cover amount offered may be limited. But this ensures that even without proof of incomel, individuals can still access protection, though within some limits.
How much coverage can you get without income proof?
When income proof is available, insurers can easily judge the ability to pay premiums. This lowers the insurer's risk and makes it possible to offer higher life cover amounts. Without income proof, the situation changes. The life cover provided is usually lower than that of standard or regular policies. Insurers often set limits on the sum assured to manage risk. The exact amount depends on the insurer’s rules, as well as other factors such as age, health, among others.
Do keep in mind that even while the cover available without income proof can be limited, it is neither insignificant nor excessive. Thus offering a crucial safety net for families.
Who should consider buying a term insurance that requires minimal documentation?
Any individual, especially those without formal regular salaries or with financial proof of employment, can benefit greatly from a term insurance plan without income proof.
This type of plan is ideal for business owners, self-employed individuals, entrepreneurs, and others with irregular income patterns. This is because even they need reliable coverage without the hassle of complicated paperwork.

Business Owners
Business owners often face fluctuating incomes and irregular documentation. A term insurance plan without income proof makes it easier for them to secure coverage.
This high degree of flexibility ensures that even without consistent income records, they can still provide financial protection for their families. Thus, it helps them stay safeguarded through uncertain times.

Self-employed individuals (Freelancers)
Freelancers or self-employed individuals can often have a great month when it comes to earning money and little or no income in the next. Such individuals with irregular income often do not have regular pay stubs or income proof.
Availing a term insurance plan without income proof, these individuals can still access reliable coverage. The simplified documentation process allows them to protect their families without the traditional barriers of income verification.

Individuals with Irregular Income
People with irregular income streams, such as seasonal workers, face challenges when applying for traditional insurance plans.
A term insurance plan without ITR provides them with an easier way to secure financial protection. This flexibility is crucial for those whose income may not follow a consistent pattern throughout the year.
Tips to get approved for term insurance without income proof
Quick Tips for Easy Approval
Good Health Record
Healthy lifestyle improves eligibility

Reasonable Coverage
Realistic cover boosts approval chances

Alternative Documents
Proof of savings shows stability

Apply Younger
Early application lowers premiums
What documents are required to buy term plan without income proof in India?
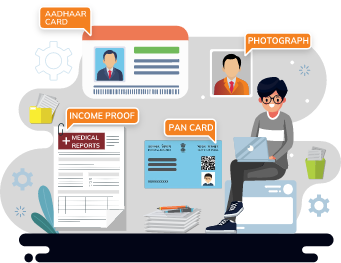
Purchasing a term insurance plan without income proof in India is straightforward. You only need a few essential documents to complete the process. These documents are designed to simplify the purchase, making sure that even those without formal income proof can get the protection they need.
 Aadhaar card
 PAN card
 Age proof
 Medical reports
 Recent passport-size photo
Frequently Asked Questions
Are term insurance medical tests mandatory?
Medical tests may or may not be mandatory for a term insurance plan without income proof, depending on the type of policy chosen, your age, coverage amount, among other factors.
Can homemakers or non-earning individuals buy term insurance without income proof?
Yes, homemakers and non-earning individuals can purchase such plans. Insurers may evaluate eligibility based on age, health, and family background.
Will my premium be higher if I buy without income proof?
Yes, usually premiums may be slightly higher as compared to regular or standard plans. This is due to perceived risk, but insurers do try to balance this with limited coverage caps.
What happens if I later provide income proof?
Submitting income proof after the policy is issued may not change the existing policy in force, in either the coverage amount or premiums. Although some insurers may allow you to increase coverage or adjust premiums accordingly.
Can I increase my coverage later if I initially buy without income proof?
This usually depends on the particular plan/policy purchased and the insurer’s guidelines and medical checks. Some plans or insurers may allow to increase coverage at a later stage while others may not.
Is there a maximum limit on the sum assured without income proof?
Yes, insurers usually impose a maximum cap on the sum assured to manage risk when income proof is unavailable.
People like you also read...